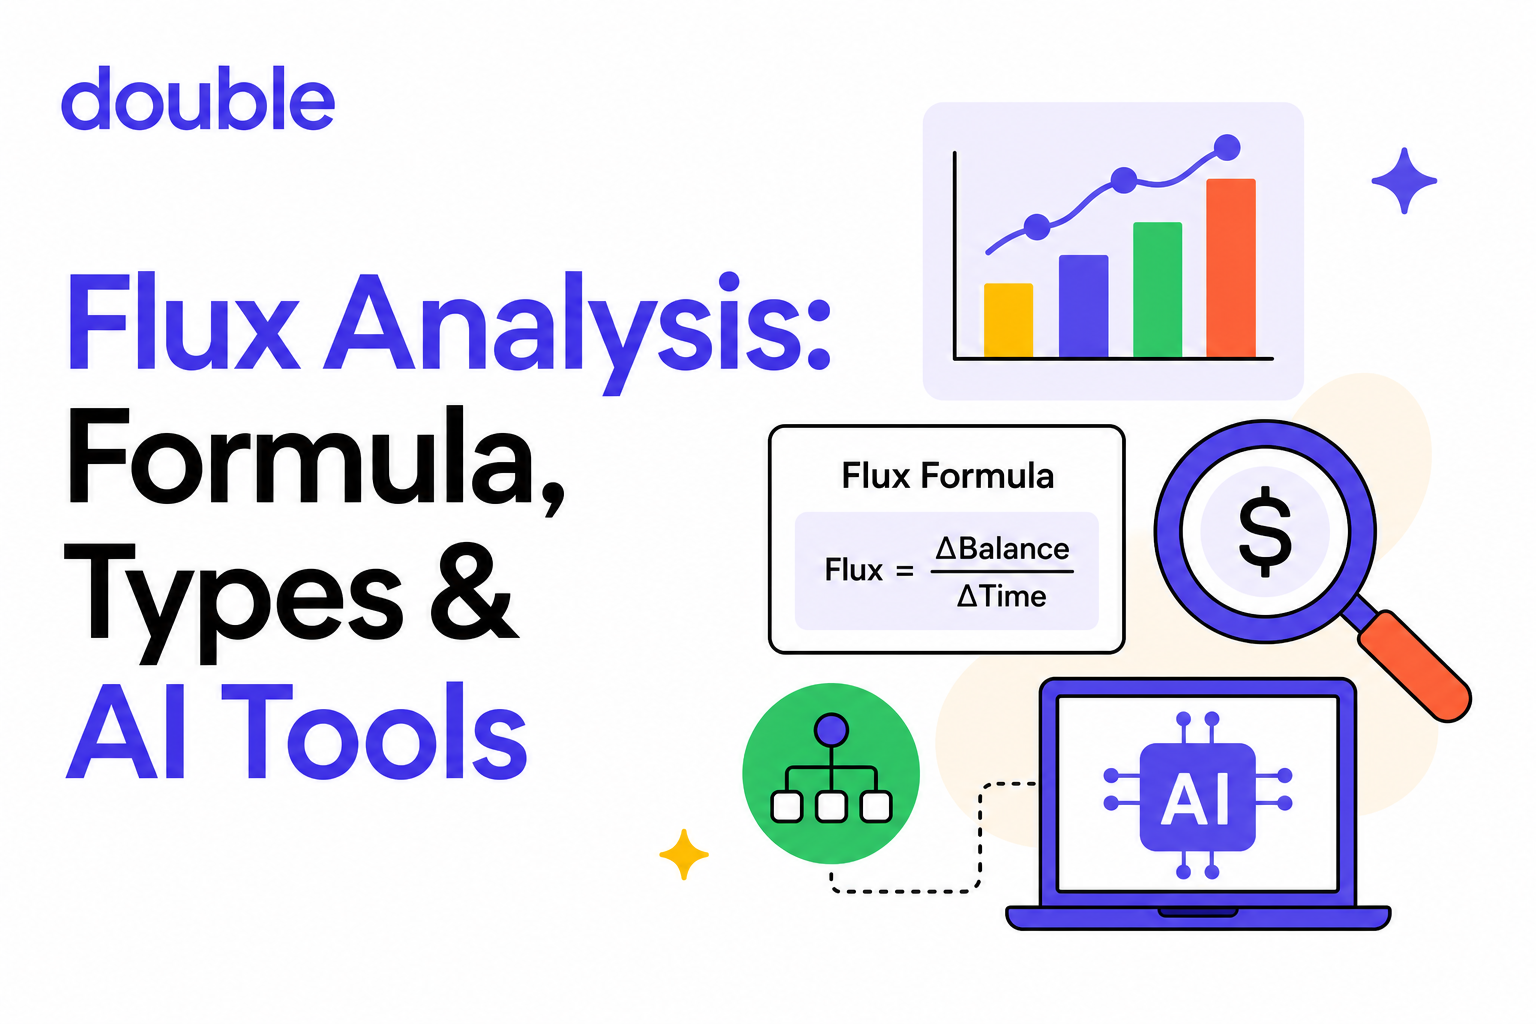
Your balance sheet and P&L moved between periods. Some of those movements matter, and some don't. Flux analysis is the process that tells you which is which, and more importantly, why. Getting that process right means fewer back-and-forth questions at close and explanations that actually stand on their own.
TLDR:
- Flux analysis compares account balances across two periods, calculates dollar variance and percentage change, and documents why each flagged movement happened.
- A strong flux explanation covers four elements: what changed, by how much, why it changed, and whether it will recur. Missing any one makes it unusable for auditors.
- Flag variances using both a dollar threshold and a percentage threshold, since a $500,000 account moving 2% and a $10,000 account moving 150% carry very different risk signals.
- Manual flux analysis breaks down on data quality, volume noise, and the hours spent exporting trial balances with no audit trail back to source data.
- Double's AI Flux Analysis drafts variance explanations at the vendor and transaction level for P&L and Balance Sheet reports, with finance teams using Double reporting 30 to 50 percent reductions in close time.
What Is Flux Analysis
Flux analysis measures and explains change between two reference points, most often two reporting periods on the balance sheet and P&L. That is the core idea underneath every version of the term, whether you found this page searching for an accounting technique or a biology method.
In accounting, flux accounting compares account balances across two reporting periods, flags the movements that matter, and documents why they happened. A controller running flux analysis on the balance sheet is asking one question: what changed, and what caused it.
Flux refers to the movement or rate of change of something measurable, and in finance that system is the general ledger.
The Flux Analysis Formula
Two numbers do the real work in flux analysis: dollar variance and percentage change.
Dollar variance = Current Period Amount minus Prior Period Amount.
Percentage change = (Current Period Amount minus Prior Period Amount) divided by Prior Period Amount, multiplied by 100.
Both matter because dollar amounts and percentages flag different risks. A $500,000 account that moved 2% might be immaterial. A $10,000 account that moved 150% might signal a coding error worth explaining.
A common approach flags anything above a set dollar amount (say, $10,000) or percentage (say, 10%), whichever triggers first. Payroll or COGS often warrant tighter percentage thresholds since small moves carry larger dollar consequences, as outlined in this guide to setting materiality thresholds by account category.
Account | Prior Period | Current Period | Dollar Change | % Change |
|---|---|---|---|---|
Advertising Expense | $20,000 | $32,000 | $12,000 | 60% |
Rent Expense | $50,000 | $51,000 | $1,000 | 2% |
Types of Flux Analysis in Accounting
Horizontal flux analysis compares the ending balances of different financial indicators over two accounting periods to spot changes in trends and patterns, according to HighRadius. It moves across the time horizon, placing March next to April or Q1 next to Q2.
Vertical analysis works differently. It reviews financial statements within a single period and expresses each item as a percentage of a base figure, according to Prophix, such as expressing every P&L line as a percentage of revenue.
P&L flux analysis leans horizontal, tracking revenue and expense accounts period over period to explain swings in gross margin or operating costs. Balance sheet flux analysis applies that same logic to cash, receivables, payables, and other position accounts. Most month-end close workflows default to horizontal analysis, with vertical analysis as a secondary lens for proportion changes a dollar variance alone might miss.
How to Conduct a Flux Analysis
Start with the data itself. Collect all relevant data for the accounts you plan to analyze, then organize the statements so they are accurate and complete, since incomplete data produces incomplete conclusions, according to Prophix.
Define scope before running any numbers. Decide which time periods you are comparing and which variables you are tracking, since clear boundaries keep results useful and prevent them from becoming exhausting, according to Prophix.
From there, the process runs in order:
- Calculate dollar variance and percentage change for each account.
- Apply your materiality threshold to filter out noise.
- Document a specific cause for every flagged line item.
- Route unresolved items to the account owner, such as a department head or budget owner, before sign-off.
Comparison period changes what you catch. Month-over-month surfaces timing errors and missed accruals while there is still time to fix them before close finalizes. Year-over-year suits accounts with known seasonality, where monthly swings would otherwise generate recurring false positives that waste review time.
Flux Analysis Examples
On the P&L, a common example is advertising expense jumping from $20,000 to $32,000, a $12,000 increase, or 60%. That movement clears both a dollar threshold and a percentage threshold, so it gets flagged and requires an explanation: a new campaign launch, a seasonal push, or a one-time sponsorship. Rent expense moving $1,000 on a $50,000 balance is a 2% change that typically falls below materiality, so it gets cleared without comment.
On the balance sheet, accounts receivable rising $80,000 month over month might trace to a single large invoice issued late in the period, with cash collection expected in the following month. That explanation covers what changed, by how much, why it happened, and whether it repeats: the four elements a strong flux explanation requires. Without that context, the movement looks like a collections problem when it is simply a timing difference.
A more complex example is payroll expense increasing 15% in a month where headcount stayed flat. Flux analysis surfaces the variance; the explanation might point to a bonus accrual, overtime in a specific department, or a payroll-timing change that pulled two pay runs into the same period. The explanation tells the reviewer whether to expect the same number next month or whether it normalizes, and that distinction is the difference between a note in the workpapers and a question that delays sign-off.
Flux Analysis vs. Variance Analysis
Both tools measure change, but they answer different questions. Flux analysis works at the account-balance level, comparing ending balances across two periods on the P&L or balance sheet and asking what caused the movement. Variance analysis compares actuals against a budget or standard cost, making it a planning and performance tool, not a period-over-period close review.
The distinction matters at close. Flux analysis tells you what happened between March and April: it catches the missed accrual, the one-time charge, the invoicing timing shift. Variance analysis tells you how April tracked against the plan: it surfaces whether the advertising spend that spiked in flux is a budget problem or simply an approved campaign. Running flux analysis first to confirm what changed, then layering in budget vs. actuals for management reporting, is the sequence most close teams follow because the two tools build on each other and do not duplicate each other's work.
Scope also separates them. Flux analysis covers every account on the trial balance; variance analysis typically focuses on the accounts with budgeted targets, which excludes many balance sheet positions. A receivables balance has no budget line, so flux analysis is the only lens available for explaining its movement. For P&L accounts with approved budgets, both lenses apply, and when they point in the same direction, the explanation for that account becomes much easier to defend to an auditor or a CFO.
Common Variance Types and Their Causes
Every flagged account falls into one of two buckets: revenue, expense, labor, material, and overhead variances, and within each bucket, one of two causes.
Revenue variances trace to pricing, volume, or product mix changes. Expense variances usually come from vendor changes, cost increases, or one-time charges. Labor variances reflect headcount adjustments, overtime, or rate changes. Material variances stem from input cost changes or volume differences, and overhead variances often trail allocation changes tied to any of the above.
Variances flagged by flux analysis trace to one of two sources: errors in the data or real changes, per Prophix. A miscoded transaction or missed accrual looks alarming but resolves with a correcting entry. A real change, a new vendor contract, a pricing shift, a seasonal spike, needs no correction, just an explanation.
What Makes a Strong Flux Explanation
A strong flux explanation stands on its own. Anyone reading it later, an auditor, a manager, a new hire, should understand the movement without pulling up the underlying data set.
Include the specific accounts involved and the dollar amount tied to each. Because many interlinked accounts affect a single fluctuation, note the cause behind every piece of the variance, according to Vena Solutions. If only part of a swing traces to a known cause, state which portion and leave the rest flagged instead of rounding up to a tidy story.
The most common failure is the one-line explanation with no dollar quantification: "travel was up this month." That sentence tells a reviewer nothing about materiality, cause, or whether it repeats next period. Auditors reviewing flux commentary months after close look for the same three things every time: a specific number, a specific cause, and a note on whether the driver is one-time or ongoing.
Challenges of Manual Flux Analysis
Manual flux analysis breaks down at a few predictable points, regardless of team size.
Data quality comes first. Accurate flux analysis depends entirely on having clean, complete data. Inconsistent account coding, missing prior period figures, or poorly structured charts of accounts can turn a quick comparison into a lengthy general ledger reconciliation exercise before any real analysis starts.
Volume creates the second problem. With hundreds of line items, flagging every fluctuation above a threshold generates noise, and teams struggle to separate variances worth investigating from those explained by timing or seasonality. Materiality thresholds only partially fix this, since no universal rule exists.
The remaining friction is mechanical. Exporting and formatting trial balances into spreadsheets every period eats hours that never show up in the final explanation, leaving no audit trail back to source data. Accounting automation targets this mechanical layer directly.
How AI Is Changing Flux Analysis
According to Gartner research cited by Finrep, 50% of organizations will use AI in financial close by 2026, up from fewer than 10% in 2022. AI accounting agents now pull actuals, flag material variances, and draft explanations at the vendor level, so reviewers check sourced conclusions instead of building them from scratch. Judgment on whether a driver is one-time or recurring still belongs with the accountant. AI eliminates the manual data work but preserves human oversight at every step. The practical change is where the time goes: less of the close spent exporting trial balances and building variance tables, more of it spent reviewing explanations that are already grounded in transaction-level detail. Beyond variance drafting, Ask Double is an AI assistant built into Double that can query ledger data on demand, run diagnostic reviews of P&L and Balance Sheet reports to surface structural issues such as negative bank balances or suspense account usage, and answer questions across entities from a single conversational interface, all with full audit logging and permission controls. On Sage Intacct, Ask Double can also stage the correcting journal entry or bill for review, so the assistant that answers a flux question can also stage the fix that follows.
AI Flux Analysis in Double
Double's AI Flux Analysis drafts variance explanations at the vendor and transaction level for both P&L and Balance Sheet reports, giving reviewers conclusions instead of a blank spreadsheet. Materiality thresholds, explanation depth, and model selection stay configurable, with stale data flagged for a one click rerun. For a controller, variance explanations stay attached to the financials themselves, so a question from management gets answered straight from the existing record even after close.
Bulk actions let a controller mark multiple accounts reviewed, copy explanations to comments/footnotes in the financials, or rerun analysis in one step. Department heads and budget owners can review expenses and give variance explanations through controlled workflows without accounting system access. Double's close management covers the rest of the close, from reconciliations to sign-offs, in one live system connected to your ERP.
Finance teams using Double report 30 to 50 percent reductions in close time, with the manual variance reconstruction step accounting for a measurable share of that saving. Pricing runs on a flat annual rate with no per-seat fees, so costs do not climb as the team grows and no enterprise rollout is needed.
Final Thoughts on Flux Analysis as a Close Discipline
Flux analysis works best when it runs the same way every period, with consistent thresholds, clear ownership, and explanations that hold up under auditor and CFO scrutiny. Finance teams get the most out of it when the controller owns it as a control. If you want to see what that looks like when AI handles the variance drafting, book a demo with Double.