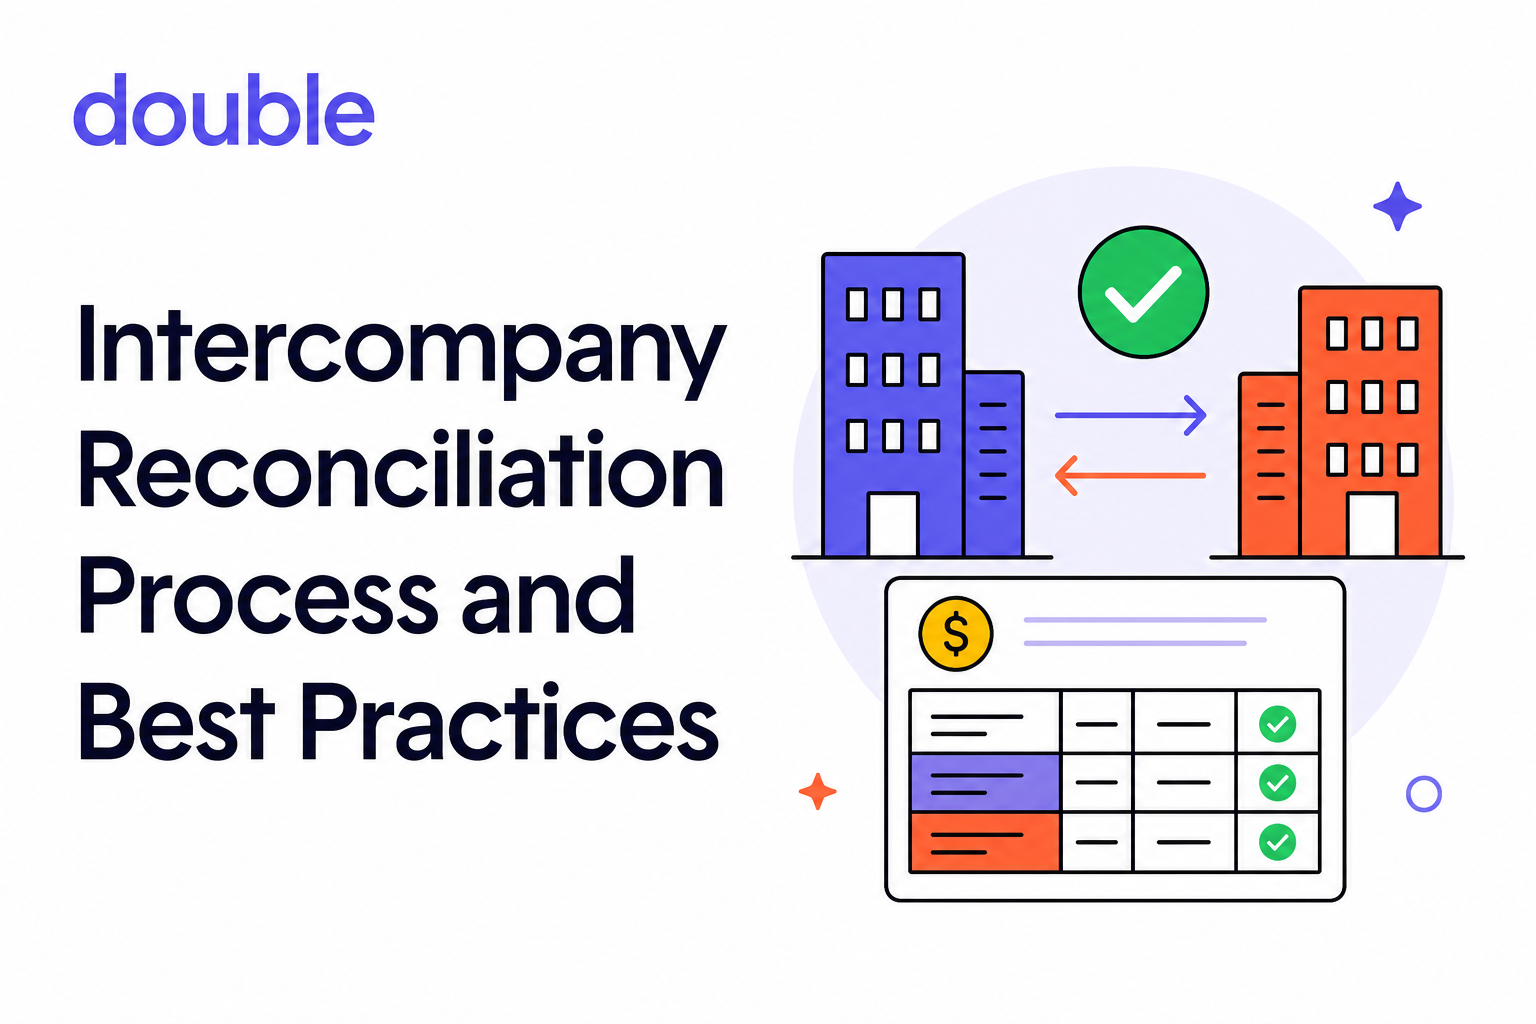
Closing the books across multiple entities means every intercompany transaction has to agree on both sides before your consolidated numbers can be trusted. That's simple in theory, but in practice you're often dealing with mismatched amounts, timing differences, and ledgers that don't talk to each other. What follows is a practical look at how the intercompany reconciliation process works and how to keep it from dragging out your close every month.
TLDR:
- Intercompany reconciliation confirms that every transaction recorded by one entity matches the counterpart entry at the other entity before consolidation.
- Four recurring challenges drive most close delays: currency gaps, timing mismatches, disconnected ledgers, and inconsistent account coding.
- An Excel matrix template maps every entity pair in a grid, with any cell that fails to net to zero flagging a pair that needs investigation.
- According to Coefficient's CFO resource on intercompany reconciliation, manual matching stretches close timelines to 7 to 10 days.
- Double automates multi-entity close workflows with two-way ledger sync into Sage Intacct and QuickBooks for corporate finance teams.
What Is Intercompany Reconciliation
Intercompany reconciliation confirms that a transaction recorded by one legal entity in a corporate group matches the corresponding entry recorded by its counterpart entity. If Entity A books a $50,000 charge for services provided to Entity B, Entity B's books need to show that same $50,000 as a payable or expense. When those entries agree, the transaction is matched. When they don't, someone has to find out why before the books close.
Most companies with subsidiaries run several general ledgers, sometimes on different ERPs, sometimes on different close calendars, sometimes managed by different regional controllers. Intercompany reconciliation keeps those separate books internally consistent before consolidation.
A parent company's consolidated financial statements should reflect only transactions with the outside world, not internal transfers, loans, and cost allocations between subsidiaries. Open balances let those internal transactions leak into consolidated numbers, overstating revenue, expenses, receivables, or payables that should have canceled each other out.
The reconciliation is the control that makes elimination entries possible and the consolidated financials trustworthy.
Common Types of Intercompany Transactions
Every corporate group generates its own recurring flavor of internal transaction, but most fall into a short list of categories.
- Sales and purchases of goods or services. One subsidiary manufactures a product and sells it to a sister entity for distribution, or a shared engineering team bills its time to another division.
- Management and shared-service fee allocations. Corporate overhead, like HR, legal, or IT, gets billed out to operating subsidiaries based on headcount, revenue, or another allocation key.
- Intercompany loans and interest. A parent funds a subsidiary's working capital, and both sides need to track the principal balance and the interest accruing on it.
- Dividend flows. A subsidiary distributes earnings up to its parent, requiring matching entries on both sets of books.
- Asset transfers. Equipment, inventory, or intellectual property moves from one entity to another, often at a transfer price that needs documentation.
- Cost recharges. Travel, insurance, or software costs paid centrally get redistributed to the entities that actually incurred them.
The Intercompany Reconciliation Process: Step by Step
The reconciliation runs in five stages, and each one has to complete cleanly before the next one starts.
- Extract balances. Each entity extracts its intercompany balances from the general ledger (receivables, payables, revenues, and expenses) and confirms those balances cover every active trading relationship for the period.
- Exchange data. Counterpart entities exchange their extracted data so each side can see what the other has recorded; this is where timing gaps and coding differences first become visible.
- Match transactions. Matching runs transaction by transaction: each entry from Entity A is paired against its counterpart at Entity B, and every pair that agrees gets cleared. Any open item (a missing entry, a wrong amount, a misrouted cost allocation) goes into an open-items log with the responsible preparer assigned to investigate.
- Resolve open items. The open items get resolved through adjusted journal entries or by obtaining supporting documentation that confirms which entity's recording was correct.
- Controller sign-off and feed to consolidation. Once all pairs net to zero, the controller signs off on the agreed intercompany schedules, and those balances feed directly into the consolidation elimination entries.
Running these stages on a fixed calendar, and not ad hoc at quarter-end, keeps the open-items log short and prevents mismatches from stacking up across periods.
Intercompany Reconciliation Examples and Journal Entries
Numbers make the logic click faster than definitions do. Three common scenarios show how the same transaction lands differently depending on which side of the ledger you're looking at, and where the mismatches tend to hide.
Scenario | Entity A entry | Entity B entry |
|---|---|---|
Product sale ($10,000) | Debit Intercompany Receivable $10,000 / Credit Sales Revenue $10,000 | Debit COGS or Inventory $10,000 / Credit Intercompany Payable $10,000 |
Intercompany loan ($100,000, 5% annual) | Debit Loan Receivable $100,000 / Credit Cash $100,000; monthly accrual: Debit Interest Receivable $417 / Credit Interest Income $417 | Debit Cash $100,000 / Credit Loan Payable $100,000; monthly accrued expenses journal entry: Debit Interest Expense $417 / Credit Interest Payable $417 |
Shared-service fee ($5,000) | Debit Intercompany Receivable $5,000 / Credit Management Fee Income $5,000 | Debit Management Fee Expense $5,000 / Credit Intercompany Payable $5,000 |
A discrepancy shows up when one side of a pair doesn't match, similar to how bank reconciliation errors surface in practice. Say Subsidiary B books the product sale at $9,500 instead of $10,000. The $500 gap usually traces back to freight or a discount that Subsidiary A included in its invoice but B excluded from its entry. Fixing it means pulling the source invoice, adjusting whichever entity's entry missed the freight charge, and matching both sides again to confirm they agree before closing the books.
Intercompany Elimination Entries Explained
Elimination entries remove the effect of intercompany transactions from consolidated financial statements so the group reports only what it earned and owes relative to the outside world. Once the reconciliation confirms that Entity A's intercompany receivable matches Entity B's intercompany payable, the consolidation journal debits the payable and credits the receivable, netting both to zero before the group's balance sheet is published. The same logic applies on the income statement: if Entity A recognized $50,000 in management fee income from Entity B, and Entity B booked $50,000 in management fee expense, both entries are eliminated so the consolidated P&L reflects neither. Unrealized profit on intercompany asset transfers gets a similar treatment: any margin built into a transfer price is deferred until the asset is sold to a third party. Loan balances between entities require a matching elimination of both the receivable and the payable, plus any interest income and interest expense recognized during the period. The reconciliation is what makes elimination entries trustworthy: a mismatch between the two sides means the elimination will be incomplete, leaving intercompany balances in the consolidated numbers and overstating either revenue, expenses, assets, or liabilities.
Common Challenges in Intercompany Reconciliation
Intercompany reconciliation gets messy fast when entities operate across different systems, currencies, and closing calendars. Four recurring challenges show up in almost every close cycle:
- Currency conversion gaps: exchange rate movement between when a transaction posts at one entity and when the counterpart records it creates variances that look like errors but are actually timing artifacts, the kind of variance storytelling covered in flux analysis.
- Timing mismatches: one entity books a transaction in June while its counterparty posts it in July, leaving open items until both sides catch up, a recurring item on any month end close checklist.
- Disconnected ledgers: entities on separate systems require manual exports and matching, multiplying the chance for typos and missed items.
- Inconsistent coding: mismatched account or entity codes hide true matches and inflate variance reports.
Intercompany Reconciliation Best Practices
Four practices separate teams that close cleanly from those that spend the last week of every month chasing open items. First, standardize your intercompany account coding across entities before the period opens. Mismatched chart-of-accounts entries are the single most common source of variances that look like errors but are actually naming inconsistencies. Second, run reconciliations on a rolling basis and avoid saving everything for the final days of close; matching transactions weekly means your open-items log stays short and discrepancies surface while the supporting documentation is still fresh. Third, assign a named owner to every intercompany relationship, and to each entity as well. When Entity A and Entity B share a trading relationship, one controller should own the match, not both, to avoid duplicated or conflicting adjustments. Fourth, lock intercompany periods on both sides simultaneously: allowing one entity to post into a closed period while its counterpart cannot will always create timing mismatches in the next cycle. Teams using a two-way ledger integration that posts reconciliation results directly to their ERP, instead of maintaining a separate spreadsheet layer, eliminate an entire class of these errors by keeping both sides of every transaction in a single system of record. For a deeper look at how these policies apply across complex multi-entity structures, HighRadius covers intercompany accounting challenges across the full reconciliation lifecycle.
How to Build an Intercompany Reconciliation Template in Excel
A usable Excel template needs a consistent row structure before any formula gets involved. Each row should capture the entity, counterparty, transaction date, description, local currency amount, functional currency equivalent, account code, and status: matched, open, or in dispute, the same structural limits that make managing accruals manually in Excel a problem at scale.
The next layer is a matrix. Instead of a flat table, it lists every entity along the rows and every counterparty along the columns, with each cell showing the net balance between that pair. A group with four entities needs a 4x4 grid, and any cell that doesn't net to zero against its mirror flags a pair needing investigation.
Entity | Sub A | Sub B | Sub C |
|---|---|---|---|
Sub A | - | $10,000 | $0 |
Sub B | ($10,000) | - | $5,000 |
Sub C | $0 | ($5,000) | - |
XLOOKUP (or VLOOKUP on older files) pulls the counterparty's recorded amount next to your own entry. Conditional formatting flags any nonzero variance row, and SUMIF rolls up totals by entity pair so you can see net exposure at a glance.
These templates work for a handful of entities and low transaction volume. Past that, version control breaks down fast, and manual matching cannot scale to daily volume across dozens of relationships without adding headcount, a core limitation covered in the month-end close process guide.
The Intercompany Settlement Process
Once you confirm which balances match, entities still need to settle who owes whom. Two approaches dominate. Cash settlement moves funds directly: the payer debits Intercompany Payable and credits Cash, while the receiver debits Cash and credits Intercompany Receivable, a workflow that accounting reconciliation software can automate. Netting offsets multiple bilateral balances so only the net difference moves, cutting transfer volume and fees, a key time and cost savings when teams automate the financial close. Non-cash options include journal entry offsets against another payable, or converting a balance into an equity contribution. Monthly netting cycles keep balances from stacking up across periods. According to Coefficient's CFO resource on intercompany reconciliation, manual matching stretches close timelines to 7 to 10 days, which is why month-end close automation has become a priority for multi-entity finance teams.
The Role of Automation and AI in Intercompany Reconciliation
Manual intercompany reconciliation forces controllers to export ledger data, build matching logic in spreadsheets, and manually investigate every open item, a process that stretches close timelines to seven to ten days and leaves open items to stack up across periods. Automation replaces that workflow by continuously comparing intercompany balances across connected ledgers, flagging discrepancies the moment they appear, not waiting until someone exports data at month-end. AI takes that a step further: instead of simply surfacing a mismatch, it analyzes the underlying transaction detail to identify whether the gap traces to a timing difference, a currency conversion artifact, or an entry that landed in the wrong account, the same diagnostic work a controller would do manually, completed in seconds. For teams on Sage Intacct or NetSuite, platforms like Double can automate the comparison between ledger balances and uploaded supporting files (including Excel and CSV) and surface discrepancies inline without manual cross-referencing. The AI-powered reconciliation workflow handles complex account types that standard bank-to-GL matching cannot reach, including intercompany accounts, clearing accounts, and prepaid schedules. The practical result is a shorter open-items log, a close that runs on a predictable calendar with no ad hoc scramble, and elimination entries that controllers can trust because the matching work behind them was systematic and not manual.
For teams that want to go further, Ask Double extends that diagnostic capability into a conversational layer: controllers can ask natural-language questions about intercompany balances, query ledger data on demand across connected entities, and trigger workflow actions, like creating a reconciliation task and assigning it to a team member, directly from the same chat interface. Ask Double can also perform on-demand diagnostic reviews of Balance Sheets, surfacing structural issues such as unresolved intercompany balances before they reach consolidation. The AI handles the data retrieval and preliminary analysis; the controller retains ownership of the investigation and sign-off.
Double for Multi-Entity Close Management
Double is built for mid-market internal finance teams managing close workflows across multiple legal entities. With two-way sync to Sage Intacct and QuickBooks Online, every reconciliation result, journal entry, and accrual posts directly to the ledger without a separate spreadsheet layer in between. Controllers can filter all reporting surfaces (P&L, Balance Sheet, Transaction Reports, and Search) by subsidiary, and select specific subsidiaries when creating journal entries or accruals, so entity-level separation is maintained across the full close workflow inside a single workspace. The AI-powered reconciliation workflow automates comparisons between ledger balances and uploaded supporting files (including Excel and CSV) and surfaces discrepancies inline without manual cross-referencing, covering non-standard account types like intercompany accounts, clearing accounts, and prepaid schedules that standard bank-to-GL matching cannot reach. AI Flux Analysis automatically drafts variance explanations at the vendor and transaction level for the P&L and Balance Sheet, with configurable materiality thresholds, so controllers start reviewing conclusions instead of rebuilding variance stories from scratch each period. The result is a close that runs on a predictable calendar with no ad hoc scramble, and elimination entries controllers can trust because the matching work behind them was systematic.
Final Thoughts on Mastering Intercompany Reconciliation
The gap between a clean close and a messy one usually comes down to how well your intercompany balances are matched before consolidation starts. Timing mismatches, currency gaps, and disconnected ledgers are solvable problems once you have a consistent process and a clear template to work from. Your elimination entries can only be as accurate as the matching work behind them. When you're ready to move beyond manual tracking, book a demo with Double to see close automation in action.